
The basic function of management accounting is to assist the management in performing its functions effectively. The functions of the management are planning, organizing, directing, and controlling. The part of accounting that helps managers in making decisions providing accounting information is called management accounting. One of the most classical examples in management accounting is variance analysis. In a nutshell, it comprises of comparing two values for the same measurement. This could be comparing actual and planned figures or two different months.
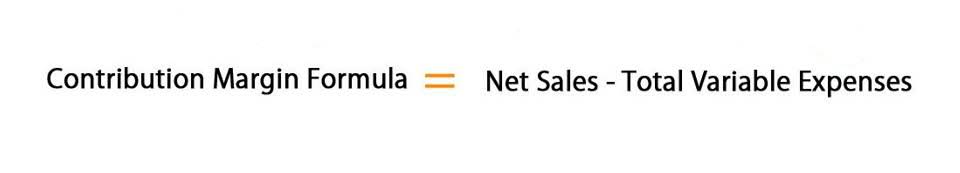
While managerial accounting focuses on providing data for internal use, financial accounting focuses on the decisions related to an organization’s financial relationship with external companies. Management accounting also includes generating reports of budgeting, trend analysis, costing, forecasting sales on weekly, daily, or monthly performance. Margin analysis is primarily concerned with the incremental benefits of optimizing production.
Why Emotional Intelligence is Key to Successful Conscious Leadership
Common financial statements include balance sheet, income statement, and cash flow statement. Furthermore, capital budgets outline potential future expenses, such as acquisitions, new equipment purchases, facility upgrades, and long-term project investments. Capital budgeting is concerned with the analysis of information required to make the necessary decisions related to capital expenditures. In capital budgeting analysis, managerial accountants calculate the net present value (NPV) and the internal rate of return (IRR) to help managers to decide on new capital budgeting decisions. While they often perform similar tasks, financial accounting is the process of preparing and presenting official quarterly or annual financial information for external use.
- Managerial accountants utilize performance reports to note deviations of actual results from budgets.
- There are a number of ways in which managerial accounting differs from financial accounting.
- Underachieving departments and employees are provided with these performance reports and called to order according to their performance metrics.
- After almost a decade of experience in public accounting, he created MyAccountingCourse.com to help people learn accounting & finance, pass the CPA exam, and start their career.
- Real Business provides readers with high profile interviews, news, insight and industry benchmark reports, as well as a growing stable of events tailored to SME growth.
Overachieving and constantly productive departments and employees are also easily identified, giving a company an idea of its most valued human assets. Outstanding invoices are tightly followed while debtors and repayment issues are easily identified. Account receivables management accounting management also helps a company avoid situations of harmfully overdue payments or total non-payment of pending receivables. These expenses span from the cost of raw materials to labor costs to factory overheads and the cost of delivering goods to buyers or consumers.
Additional Resources
When there are deviations from the stated objectives, managers must decide what modifications are needed. Reading – Management accounts are designed specifically to meet the information needs of managers in the organisation. The accounts team sets out key topics and analysis required to monitor performance with customised reporting aligned to their income statements. Cost managerial accounting reports help businesses to compare the total cost of producing goods or services with the selling price for each unit.
Revenue missed budget by £0.2m due to supply chain delays stalling product launches, but still showed 5% growth on prior year. Gross margin remained steady at 36% as cost inflation was passed to the market. Higher operating costs stemmed from increased staff and additional marketing to protect market share amid competitor discounting.
Revaluation Accounting
The objective is to maximize profit through the use of the best alternative method. It provides costing and statistical data to be utilized in setting goals and formulating future policies. While these functions are initially stated in qualitative terms, most of these items would at some point be translated into a dollar value or dollar effect.
The basic rule applying here is that a product should be manufactured in-house if the relevant cost is lower than the cost of purchasing the product. To determine the relevant cost, it is important to distinguish between two cases. If the economist (accountant, analyst) plans to record income items, then the same directory can be created for this purpose.